
What are the prerequisites for financial success? Do you need to get a high-paying job or win the lottery and bag millions of dollars overnight? Contrary to what a lot of people believe, earning money is not the only viable way to be financially stable. There are several tips for financial success you should learn today.
Taking your finances from point A to point B requires certain actionable steps. This post will discuss them comprehensively and position your mindset in the right direction for financial success. Let’s dig in!
What Is Financial Success?
Financial success is the ideal situation where you no longer have to worry about money. Financially successful people are able to fund their biggest dreams, retire early, and enjoy a more fulfilled life.

10 Essential Tips For Financial Success
Are you ready to learn what it takes to succeed financially? Here are some of the best pieces of advice that will help you take your finances to the next level:
1. Plan For Retirement Early
Retirement planning is crucial for ensuring a financially secure and fulfilling future. Aside from being one of the steps to financial success, this is one way to reward yourself after decades of hard work.
Firstly, planning for retirement early can prepare you for living expenses after you stop earning a salary. This will enable you to maintain your desired lifestyle expenses without depending on employment.
Besides, another reason why early retirement is key is that it guarantees your peace of mind. By the time you crawl into your safety net of investments, you can focus on enjoying your golden years without worrying about running out of money. This is one of the long-term financial goals you must spend decades planning for.
2. Set Up An Emergency Fund
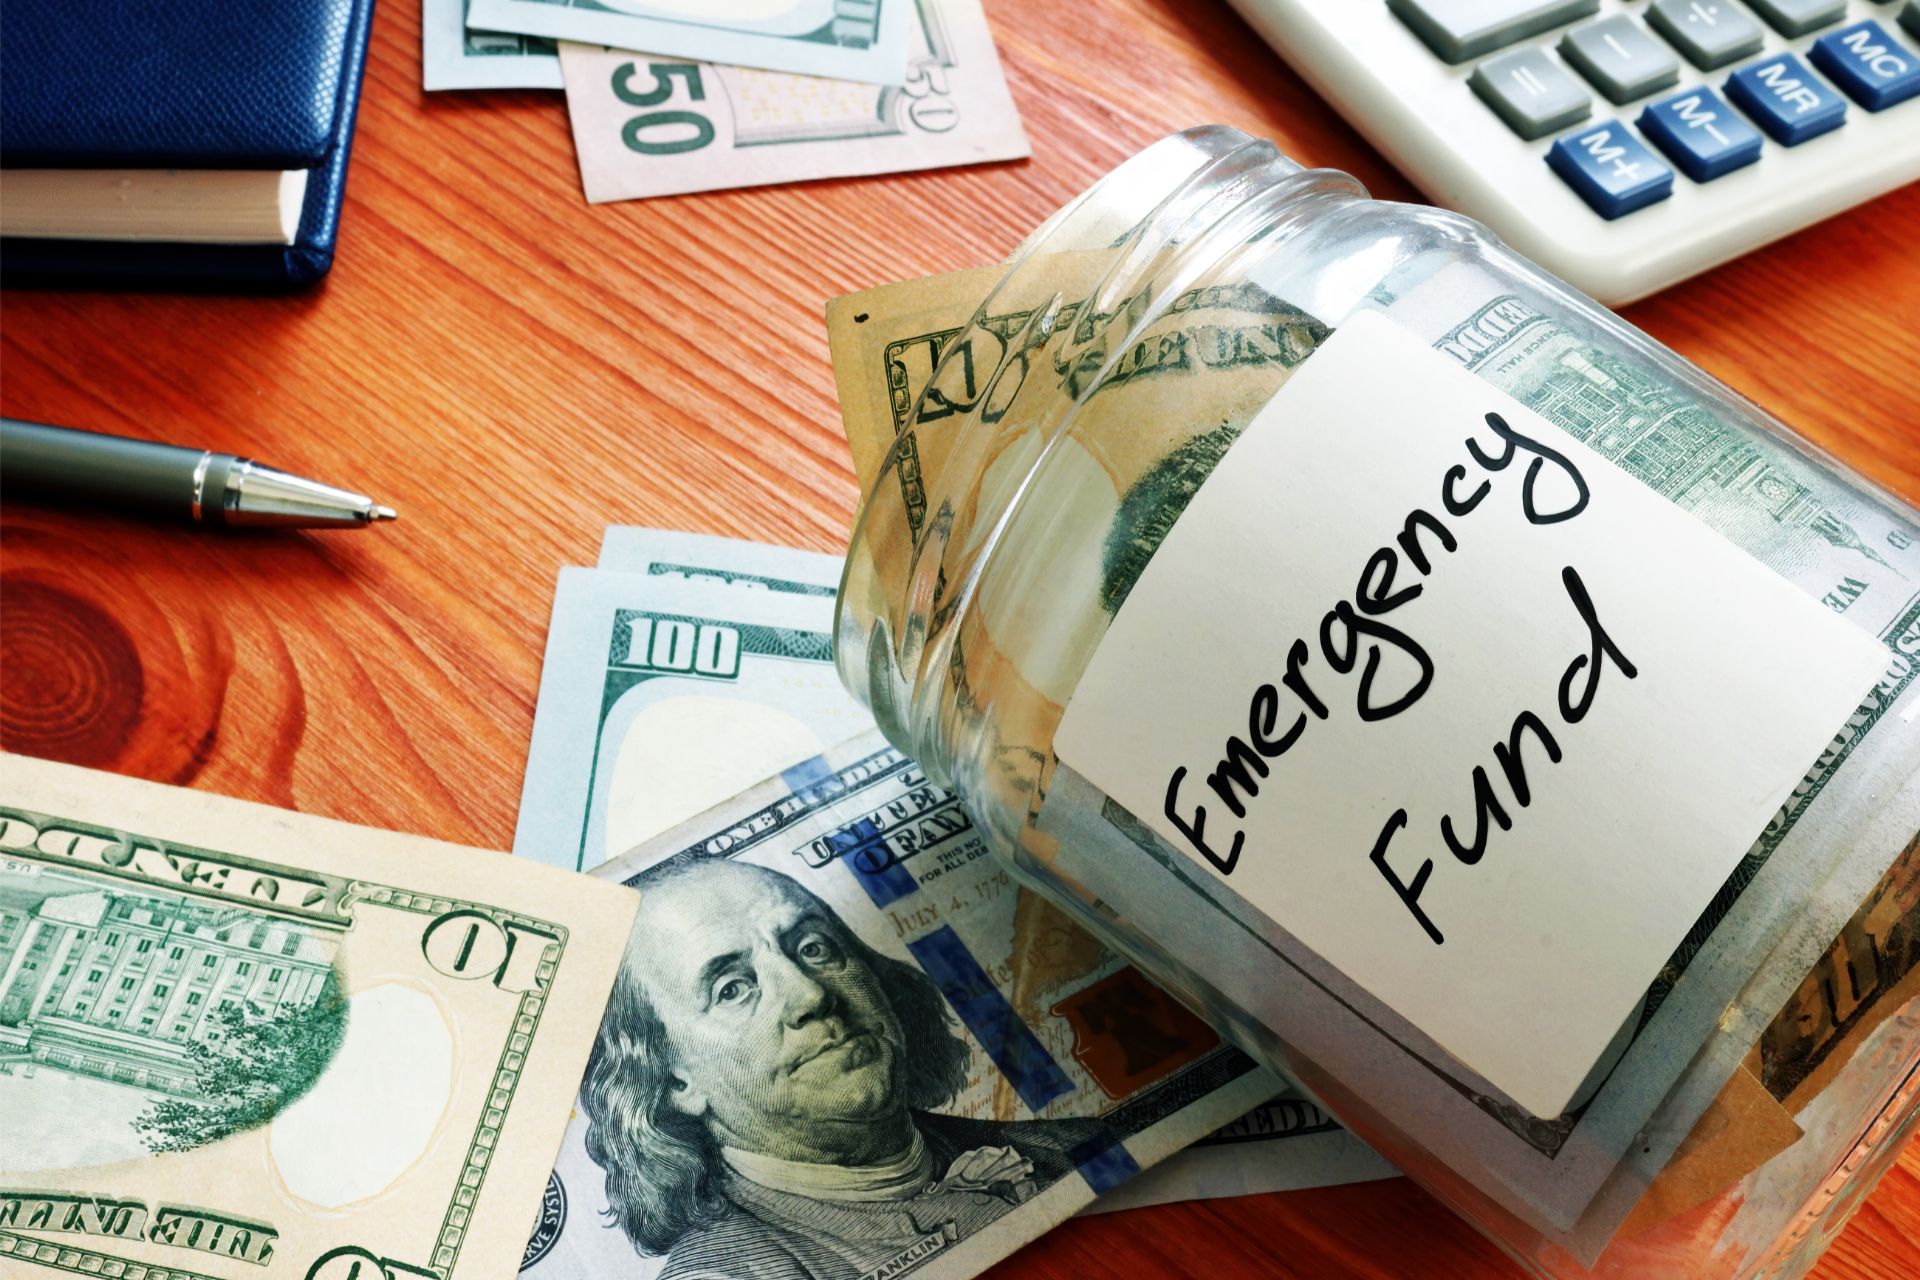
If you want to be protected from life’s financial curveballs, this is one of the top tips for financial success you should know.
Emergencies like car repairs, appliance breakdowns, or sudden medical bills can wreak havoc on your budget. But when you build an emergency fund, it allows you to handle these situations without going into debt or dipping into retirement savings.
People often get into debt when faced with unexpected costs. This is because they rely on credit cards or high-interest loans to cover many unforeseen expenses. In no time, they are roped into debt. Planning for emergencies can help you avoid this burden, as you save money on interest payments in the long run.
On the other hand, have you ever thought about what would happen if you suddenly lost your job? An emergency fund can help cover your essential expenses like rent, utilities, and groceries for a few months until you find new employment.
3. Build A Budget

Budgeting is one of the simple secrets for financial success. It is a fundamental step toward creating a financial situation that is stable and free from debt.
Although people may sometimes think budgeting isn’t important, it’s a brilliant way to gain control of your spending and focus on key financial goals.
Whether it’s saving for a house, a dream vacation, or retirement, a budget helps allocate funds toward those goals. It turns your aspirations into actionable steps by showing you how much you need to save and how adjustments to your spending can help you get there faster.
Moreover, building a budget can indirectly reduce financial stress. How? Here’s the thing. The uncertainty of your financial situation can be a significant source of stress. A budget eliminates that by giving you a clear view of your income and expenses. Knowing you have a plan for your money reduces anxiety and allows you to focus on other aspects of life.
By the way, if you would like to learn the actionable steps to building a budget for your income, here’s a post that explains budgeting in 6 simple steps.
4. Seek Financial Education
Financial literacy empowers you to make informed decisions about your money. This is how you understand financial products, investment options, and potential risks.
As you learn about your finances continually, you’ll have the confidence to deal with common financial setbacks and manage your situation.
Aside from making decisions in the present, receiving financial education can prepare you for future eventualities. It helps you to plan for major life milestones like retirement or buying a house.
So, how do you learn about money? You can get started by studying core principles from financial experts like Dave Ramsey or other successful individuals. For example, reading books or listening to podcasts on personal finance can give you insight into how to make better financial decisions.
Remember that financial education is a lifelong journey, and there are always new things to learn as your financial goals and circumstances evolve.
5. Don’t Spend On Credit
This is one of the keys to financial success. Even though credit cards can help you build a healthy credit history, you need to be careful of what you spend on credit.
Firstly, credit cards can be a trap for impulse spending. The ease of swiping a card or using tap-to-pay can make it feel like you’re spending less than you actually are. This will lead to debt with high interest rates.
Bear in mind that if you only pay the minimum amount due on your credit card, it can take a long time to pay off the balance entirely. The interest keeps adding up, making the overall debt bigger. This can be stressful as it strains your finances.
You may not be able to cut out credit cards completely to use only cash or a debit card. However, you can drastically reduce the number of purchases you make on credit. If you don’t max out your credit card, it’ll be easy to pay off your balance on time.
6. Monitor Your Taxes
You may not hear about this all the time, but it’s one of the tips that can help you achieve financial success.
Monitoring your taxes goes beyond just keeping an eye on tax rates. It’s about staying informed and organized throughout the year to ensure a smooth and potentially beneficial tax filing process.
By keeping track of your income, deductions, and expenses throughout the year, you can ensure your tax return is accurate when filing time comes. This reduces the risk of errors that could lead to delays, audits, or even penalties from the tax authority.
On the other hand, monitoring your taxes can help you to be prepared for unexpected events. You know how life can be unpredictable. Switching jobs, paying medical bills, or making charitable contributions can all impact your tax situation. Monitoring your taxes throughout the year allows you to adjust your withholding or estimated tax payments as needed to avoid owing taxes at filing time.
If you need help monitoring your taxes, here are some tips for you:
- Learn to keep records: Do well to save receipts, invoices, and other documentation related to your income, deductions, and expenses. Online record-keeping tools can also be helpful.
- Categorize your expenses: Don’t forget to track your spending throughout the year by categorizing expenses like medical bills, charitable donations, or work-related costs.
- Review tax law changes: Remember that tax laws can change from year to year. So, staying informed about any updates ensures you’re taking advantage of all the current deductions and credits.
- Consider tax software or an accountant: Sometimes your tax situation can be complex. You can’t figure it out all by yourself. It’s a good idea to seek help from a tax professional who can understand your situation better and recommend the right steps to take.
7. Protect Your Health
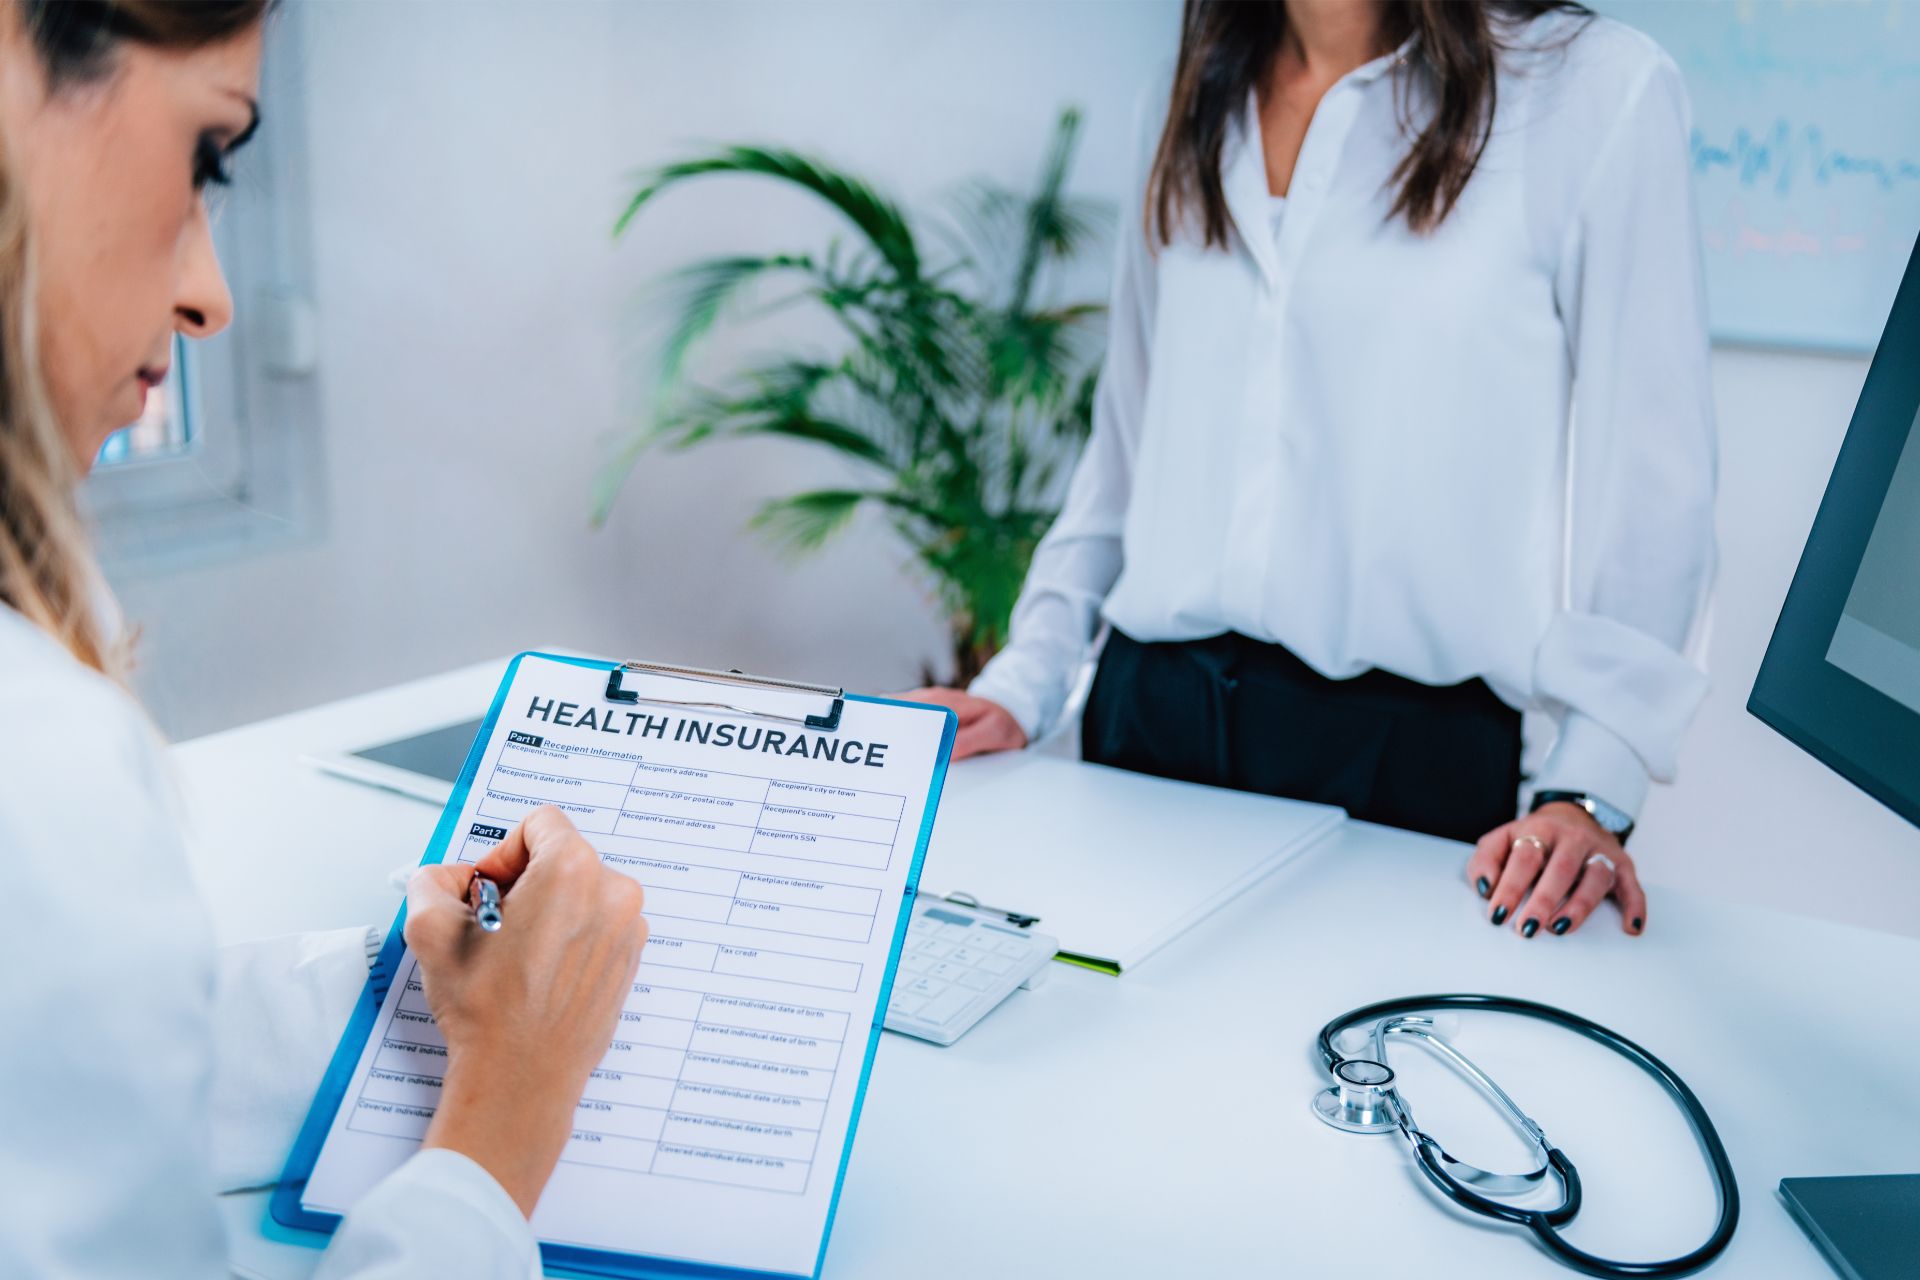
Applying for health insurance should be a top priority if you are uninsured.
Depending on the organization where you work, your employer might provide health insurance, which could include high-deductible plans that allow you to save money on premiums and get access to a Health Savings Account (HSA).
Under the Affordable Care Act (ACA), which was passed in 2010, you can be allowed to continue using your parent’s health insurance if you are under 26.
So, why is this one of the brilliant tips for financial success? If your health isn’t projected, you can quickly get into debt trying to pay huge medical bills when you fall ill.
Look at the federal and state insurance plans provided by the ACA’s Health Insurance Marketplace when you’re ready to get insurance. You can also compare deals from several insurance companies to decide which option is the best.
8. Save And Invest

Given that you still have thirty or forty years until you retire, you may ask yourself if it’s important to save and invest early.
The fact that you are still young is precisely the reason it is advisable to begin making contributions to an investing account right away. Your savings will increase enormously as your interests compound over several decades.
Let’s take an example where you start investing $150 every month from age 25. With an average yearly return on your investments of 8%, you will have roughly $1.1 million in your account after 40 years.
Investing doesn’t have to be complicated to begin with. You can get started by contributing to a 401(k), especially if your company makes matching contributions.
Alternatively, an individual retirement account (IRA) is a simple place to start if you don’t have access to a 401(k). You can open an account and add passive management investments to your portfolio, such as exchange-traded funds and index funds. This is one of the best tips for financial success.
9. Pay Your Bills On Time
If you aren’t paying your bills on time, you’re making a big mistake. It’s one of the common ways people lose money without even knowing.
You must understand that late fees can add up quickly. Avoiding them by paying on time keeps more money in your pocket. Some companies even offer discounts for early payments.
Paying bills on time is also another great way to maintain good credit. When you have an impressive credit history, you’ll be able to borrow money easily and get good interest rates. This way, you can save a significant amount of money on loans for things like cars and houses.
10. Cut Back On Recurring Charges
Recurring charges can silently drain your finances. Even small monthly fees can add up significantly over time. So, cutting back frees up money you can allocate toward savings, debt repayment, and other financial goals.
Besides, when it comes to budgeting, reducing the amount spent on recurring charges will allow you to create a more realistic budget that works for your financial situation.
If you need help cutting back, here are some tips you’ll find useful:
- Review Bank Statements: Since recurring charges are usually deducted directly from your bank account, carefully examine your bank and credit card statements to identify them.
- Evaluate Necessity: For each recurring charge, ask yourself if it’s truly necessary. How often do you use the subscription service? Do you use it at all? Can you find a cheaper alternative? If the charges are not relevant, cut them out.
- Cancel Unused Subscriptions: Don’t hesitate to cancel subscriptions or services you no longer use or need. Many companies make it possible to cancel online, while others might require a phone call.
- Renegotiate Rates: For services like cable or internet, you can contact the provider and try to negotiate a lower rate. Sometimes, threatening to cancel can prompt them to offer a better deal.
- Explore Free Alternatives: Many paid services have free alternatives. For instance, there are free sites like Netflix that offer you countless films without any subscription fee. Using free options instead of premium memberships will save you money.
11. Save Up For Big Purchases (Bonus Tip)

Saving up for big purchases is one of the simple tips for financial success.
If you want to pay for a large purchase without being prepared, you may be tempted to take a loan or resort to credit card use. While this leads to debt, the accumulated interest charges will also increase the overall cost of the item. However, saving beforehand eliminates these extra fees and allows you to purchase the item outright.
Moreover, saving for a big purchase cultivates the ability to delay gratification. It teaches you to prioritize long-term goals over temporary wants. This is a healthy habit that promotes responsible financial behavior.
Final Words On Essential Tips For Financial Success
Attaining financial success requires years of effort and commitment to your goals. The financial habits you develop in the process will drive your lifestyle and determine how successful you’ll become eventually. So, it’s best to build good money habits to keep your finances under control.
Using the tips for financial success discussed in this post, you can build a working budget, plan for retirement, and do every other crucial thing that is necessary for actualizing your ultimate goal.
Pin this for later!
